YOUR INCOME RELIES ON YOU WORKING
Real advice on Income Protection for individuals, the self-employed, business owners and employers.
Start Quote

Don’t let your income stop if you do
Because the mortgage, rent, bills and everything else you pay for don’t stop just because your income does
What is Income Protection?
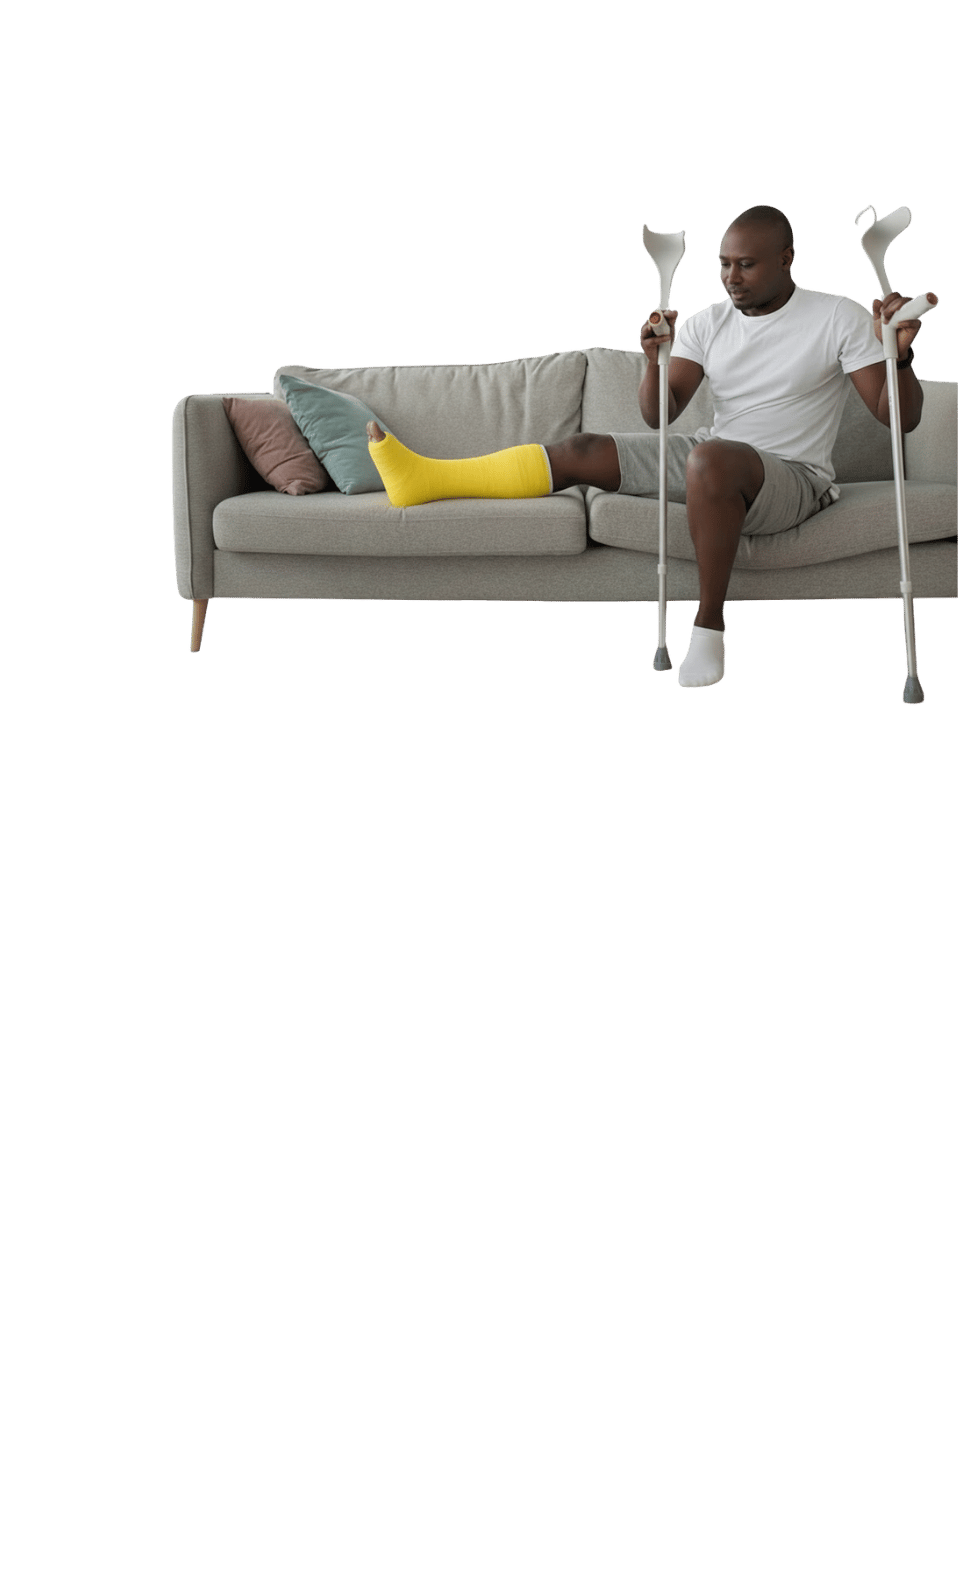
The simplest way to think about Income protection is like a personal sick pay arrangement. It’s there to pay you a monthly income if an accident or sickness means you can’t work.
Income Protection can be a lifeline when your income stops, and you can shape the cover to suit you, how much it pays out, how long it pays out for and when it pays out.
Start my review
How much can Income Protection
pay me?
&
what does
it cost?
Income Protection will usually cover around 50% to 70% of your gross income. Personal Income Protection benefits are normally paid tax-free, which is one reason insurers don’t usually cover 100% of your income.
The aim isn’t to insure every pound. It’s to work out how much you need to keep life running if you couldn’t work.
What you pay depends on your age, job, health and amount you want to insure. There are lots of ways to manage the cost, from waiting longer before it starts to pay out to a shorter claim period such as 3, 12, or 24 months.
Start Quote
We’ve got you...
We compare Income Protection from a range of leading insurers and Friendly Societies, including LV=, L&G, Aviva, National Friendly and Shepherds Friendly.
Comparing Income Protection isn't just about price. We'll help you understand the differences in cover that actually matter to you, whether you’re taking out your first policy or reviewing an existing one.
...we’re here to help.
Start Quote
£880 million paid in Income Protection claims
UK insurers paid £880 million in individual and workplace Income Protection claims in 2025*
*individual and group claims using data from the ABI and GRiD
For you
Your income powers your life and supports your goals. If illness or injury stops you working, income protection can help keep the money coming in, meaning you stay in control of your bills, your plans and your future.
For them
If your family relies on your income, being unable to work affects them too. Income Protection can help take some of the financial pressure away, giving you one less thing to worry about while you focus on getting better
With us
“Richard was really helpful and honest, I felt that he was tailoring the options to my circumstances. Great service!”
- Victoria - Legacy Is Customer Review
Local Service. Human Advice.
Income Protection advice in Cirencester and the Cotswolds.
Based in Cirencester Legacy Is was founded by Richard Kerton, a Cotswolds resident for over 35 years with two decades of experience in Life & Health Insurance.
From individuals to the self-employed and company directors, we help people across Cirencester and the Cotswolds work out how much income protection they need and what would happen financially if they couldn’t work. When your income depends on you being able to work, having somebody understand how you actually earn money matters.
Local enough to sit down with you. Experienced enough to compare the market.
Start my review
Your Income Protection questions answered
We love to answer your questions but if you don’t see what you’re looking for, get in touch!
Is Income Protection worth it if I already get sick pay?Probably. The real question is how much sick pay you get and how long it lasts. Income Protection can be set to start when your employer sick pay ends, rather than paying for cover you don’t need. Most employers won’t pay you indefinitely.
How long before Income Protection starts paying?It could start from Day 1, but most policies have a deferred period. This is the time you wait before payments begin. If you have six months of sick pay or savings, you might choose to wait longer. If you only have a few weeks, you may want payments to start sooner. Generally, the longer you can wait, the lower the premium.
How long does Income Protection pay out for?I’ll answer this with another question - How long do you want it to pay out for? Long-term cover can pay up to retirement, whilst some short term options could just pay out 3 months. We review your situation and advise on the best term for you.
Does Income Protection cover mental health and stress?Yes, it can. Mental health conditions are a major reason people are unable to work, but insurers may treat existing symptoms or previous treatment differently, so the underwriting really matters. 1 in 5 income protection claims paid in 2025 were related to time off for mental illness & stress*
Do I have to answer lots of medical questions to get income protection?Usually, yes. Traditional Income Protection that’s designed to pay until retirement normally involves a full health questionnaire, and sometimes further medical evidence. That said, some newer and shorter-term policies use simpler underwriting, shorter health questions or moratorium-style options instead.
Can I get Income Protection if I’m self-employed?Yes, and arguably this is where it can matter most because there may be no employer sick pay to fall back on. The policy can be built around how you earn and how long you could manage without an income.
Can company directors protect salary and dividend income?Yes, depending on the insurer and how your income is structured. Directors can often take salary and dividends into account, and Executive Income Protection may allow the company to arrange the cover for you.
Start Quote
Income Protection for your situation.
Individuals and Families
Income Protection for people who rely on their earnings to support their lifestyle, family, home and financial commitments.
Business Owners & Directors
With dedicated products for Directors and the self-employed. Income Protection can make a difference where you are your own safety net.
Employers
Group Income Protection can provide valuable financial support if an employee is unable to work, all while adding real value to your employee benefits.
What we do

About
YOUR INCOME RELIES ON YOU WORKING
Real advice on Income Protection for individuals, the self-employed, business owners and employers.
Get Income Protection Quotes
Don’t let your income stop if you do
Because the mortgage, rent, bills and everything else you pay for don’t stop just because your income does
What is Income Protection?
The simplest way to think about Income protection is like a personal sick pay arrangement. It’s there to pay you a monthly income if an accident or sickness means you can’t work.
Income Protection can be a lifeline when your income stops, and you can shape the cover to suit you, how much it pays out, how long it pays out for and when it pays out.
Start my Income Protection review
How much can Income Protection pay me — and what does it cost?
Income Protection will usually cover around 50% to 70% of your gross income. Personal Income Protection benefits are normally paid tax-free, which is one reason insurers don’t usually cover 100% of your income.
The aim isn’t to insure every pound. It’s to work out how much you need to keep life running if you couldn’t work.
What you pay depends on your age, job, health and amount you want to insure. There are lots of ways to manage the cost, from waiting longer before it starts to pay out to a shorter claim period such as 3, 12, or 24 months.
Get Income Protection Quotes
We’ve got you...
We compare Income Protection from a range of leading insurers and Friendly Societies, including LV=, L&G, Aviva, National Friendly and Shepherds Friendly.
Comparing Income Protection isn't just about price. We'll help you understand the differences in cover that actually matter to you, whether you’re taking out your first policy or reviewing an existing one.
...we’re here to help.
Start my Income Protection review
£880 million paid in Income Protection claims
UK insurers paid £880 million in individual and workplace Income Protection claims in 2025*
*individual and group claims using data from the ABI and GRiD
For you
Your income powers your life and supports your goals. If illness or injury stops you working, income protection can help keep the money coming in, meaning you stay in control of your bills, your plans and your future.
For them
If your family relies on your income, being unable to work affects them too. Income Protection can help take some of the financial pressure away, giving you one less thing to worry about while you focus on getting better
With us
“Richard was really helpful and honest, I felt that he was tailoring the options to my circumstances. Great service!”
- Victoria - Legacy Is Customer Review
Local Service. Human Advice.
Income Protection advice in Cirencester and the Cotswolds.
Based in Cirencester Legacy Is was founded by Richard Kerton, a Cotswolds resident for over 35 years with two decades of experience in Life & Health Insurance.
From individuals to the self-employed and company directors, we help people across Cirencester and the Cotswolds work out how much income protection they need and what would happen financially if they couldn’t work. When your income depends on you being able to work, having somebody understand how you actually earn money matters.
Local enough to sit down with you. Experienced enough to compare the market.
Start my Income Protection review
Your Income Protection questions answered
We love to answer your questions but if you don’t see what you’re looking for, get in touch!
Is Income Protection worth it if I already get sick pay?Probably. The real question is how much sick pay you get and how long it lasts. Income Protection can be set to start when your employer sick pay ends, rather than paying for cover you don’t need. Most employers won’t pay you indefinitely.
How long before Income Protection starts paying?It could start from Day 1, but most policies have a deferred period. This is the time you wait before payments begin. If you have six months of sick pay or savings, you might choose to wait longer. If you only have a few weeks, you may want payments to start sooner. Generally, the longer you can wait, the lower the premium.
How long does Income Protection pay out for?I’ll answer this with another question - How long do you want it to pay out for? Long-term cover can pay up to retirement, whilst some short term options could just pay out 3 months. We review your situation and advise on the best term for you.
Does Income Protection cover mental health and stress?Yes, it can. Mental health conditions are a major reason people are unable to work, but insurers may treat existing symptoms or previous treatment differently, so the underwriting really matters. 1 in 5 income protection claims paid in 2025 were related to time off for mental illness & stress*
Do I have to answer lots of medical questions to get income protection?Usually, yes. Traditional Income Protection that’s designed to pay until retirement normally involves a full health questionnaire, and sometimes further medical evidence. That said, some newer and shorter-term policies use simpler underwriting, shorter health questions or moratorium-style options instead.
Can I get Income Protection if I’m self-employed?Yes, and arguably this is where it can matter most because there may be no employer sick pay to fall back on. The policy can be built around how you earn and how long you could manage without an income.
Can company directors protect salary and dividend income?Yes, depending on the insurer and how your income is structured. Directors can often take salary and dividends into account, and Executive Income Protection may allow the company to arrange the cover for you.
Income Protection for your situation.
Individuals and Families
Income Protection for people who rely on their earnings to support their lifestyle, family, home and financial commitments.
Business Owners & Directors
With dedicated products for Directors and the self-employed. Income Protection can make a difference where you are your own safety net.
Employers
Group Income Protection can provide valuable financial support if an employee is unable to work, all while adding real value to your employee benefits.