Life can change before it ends
Human advice on Critical Illness Cover for individuals, families, business owners and employers
Start Quote

Critical Illness Cover helps protect the life you’re still living
1 in 2 people diagnosed with cancer are now expected to survive for 10 years or more
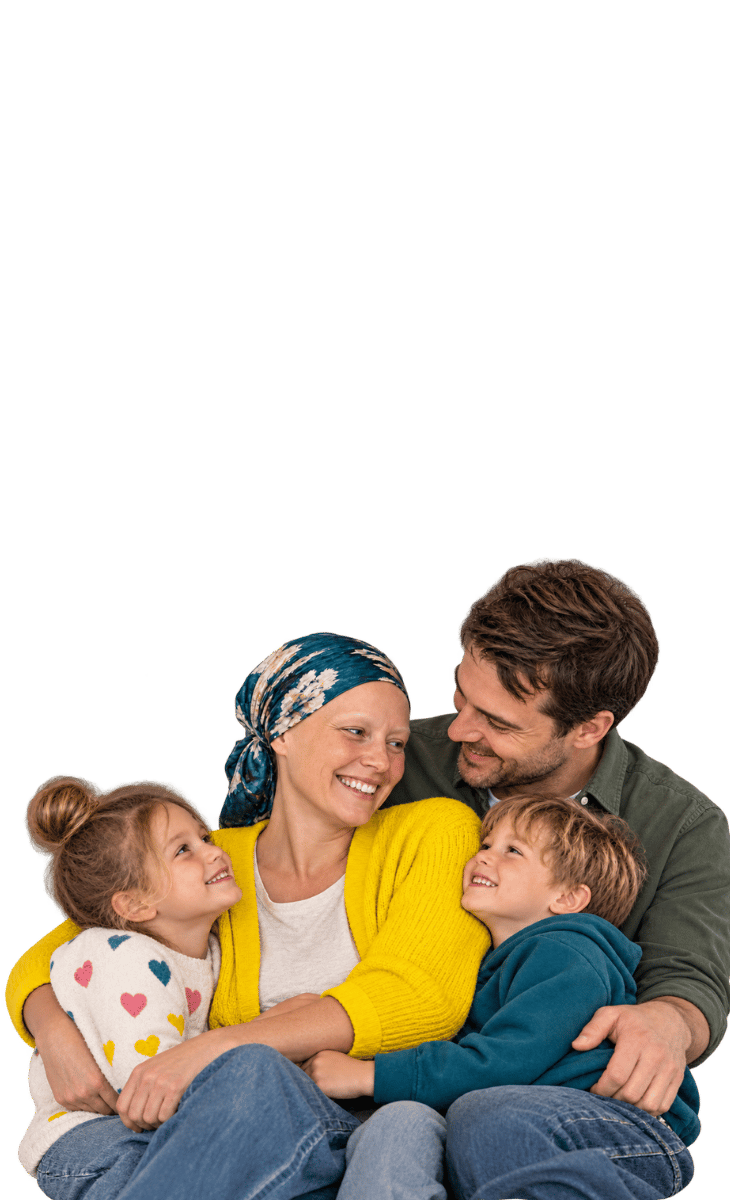
Surviving is the good news. But surviving can change your income, work, family life and finances.
Start my review
What is Critical Illness Cover?
Critical Illness Cover, sometimes referred to as Serious Illness Cover pays a tax-free lump sum if you’re diagnosed with one of the serious illnesses covered by your policy. Cancer, heart attack and stroke are the best-known conditions, but many policies now cover dozens of others and can include children’s cover too.
Unlike life insurance that pays if you die, Critical Illness Cover pays if you survive a serious illness. The money is yours to use however you need it, often it’s used to pay off a mortgage, pay for private treatment, home improvements or simply to take time out of work to fully recover at your pace without the financial stress of needing to return to work.
Start my review
How much Critical Illness Cover do I need & what does it cost?
Critical Illness Cover is priced around things like your age, health, smoking status, how long you want the cover for and the amount you choose. So for some people it may only cost a few pounds a month, for others it can be a lot more based on their circumstances and what they want the policy to cover.
So how much cover do you need? There isn’t one right answer. We start with what you’d want the money to do if you were diagnosed with something serious.
Would you want a year’s income so you could take time away from work? Clear the mortgage? Make changes at home? Or simply have enough money to give you and your family more choices while you recover?
Understanding why you want Critical Illness Cover is usually the best place to start working out how much you need. So, what would you want the money to do?
Start Quote
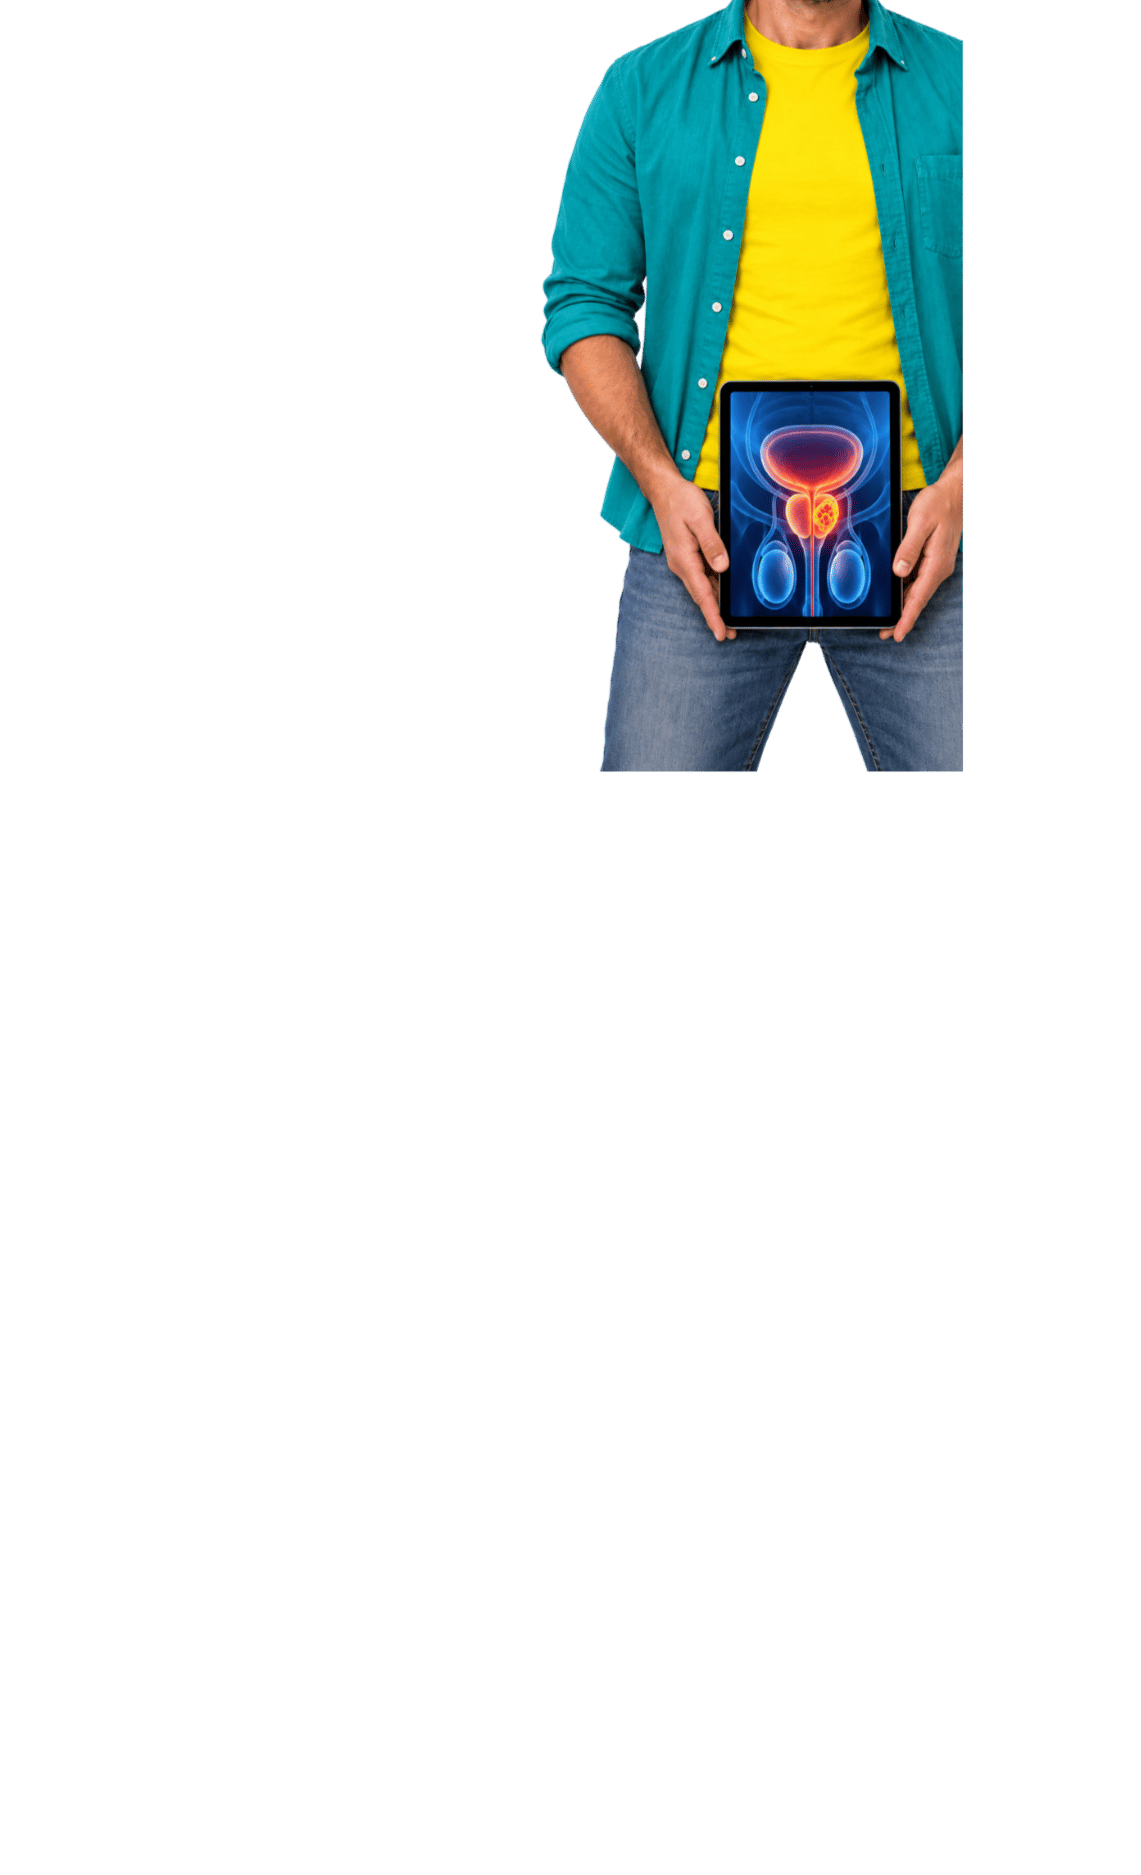
What does Critical Illness Insurance cover me
for?
2 in 3 claims are for cancer*
We’ve already talked about what you can do with the money. But what actually makes the policy pay?
Critical Illness Cover pays a lump sum when you’re diagnosed with one of the conditions covered by your policy and it meets the insurer’s definition.
Cancer, Heart Attack and Stroke account for 8 in 10 claims*, but people also claim for things like multiple sclerosis, benign brain tumours, heart valve surgery, coronary artery bypass surgery and Parkinson’s disease.
Start my review
We’ve got you...
We compare Critical Illness Cover and Serious Illness Cover from a range of leading insurers, including L&G, Aviva, Royal London, Guardian, Zurich and Vitality.
Comparing Critical Illness Cover isn’t just about price. We’ll help you understand the differences in cover that actually matter to you — whether you’re taking out your first policy or reviewing an existing one...
...we’re here to help.
Start Quote
£1.42 Billion paid in Critical Illness Claims*
UK insurers paid £1.42 billion in individual and group Critical Illness Cover claims in 2025*
*individual and group claims using data from the ABI and GRiD
For you
A serious diagnosis can change your health, work and plans overnight. A tax-free cash lump sum gives you more choices about what happens next.
For them
If you’re seriously ill, the people around you feel it too. If it’s your child who becomes ill, the impact can be even greater. Critical Illness Cover can help reduce some of the financial pressure on the whole family while you focus on what matters.
With us
“A passion for finding people the right insurance solutions. No pressure and on hand to answer questions. It was a pleasure dealing with him.” - David - Legacy Is Customer Review
Critical Illness Cover for your situation.
Individuals and Couples
Critical Illness Cover for you and/or your partner, helping protect your household finances and lifestyle if serious illness changes what you can do.
Business Owners & Directors
Personal Critical Illness Cover can protect your own finances, while business protection can help where illness affects the company too.
Children & Families
A serious illness can affect the whole family. Critical Illness Cover can help give better financial options if you or your child become seriously ill.
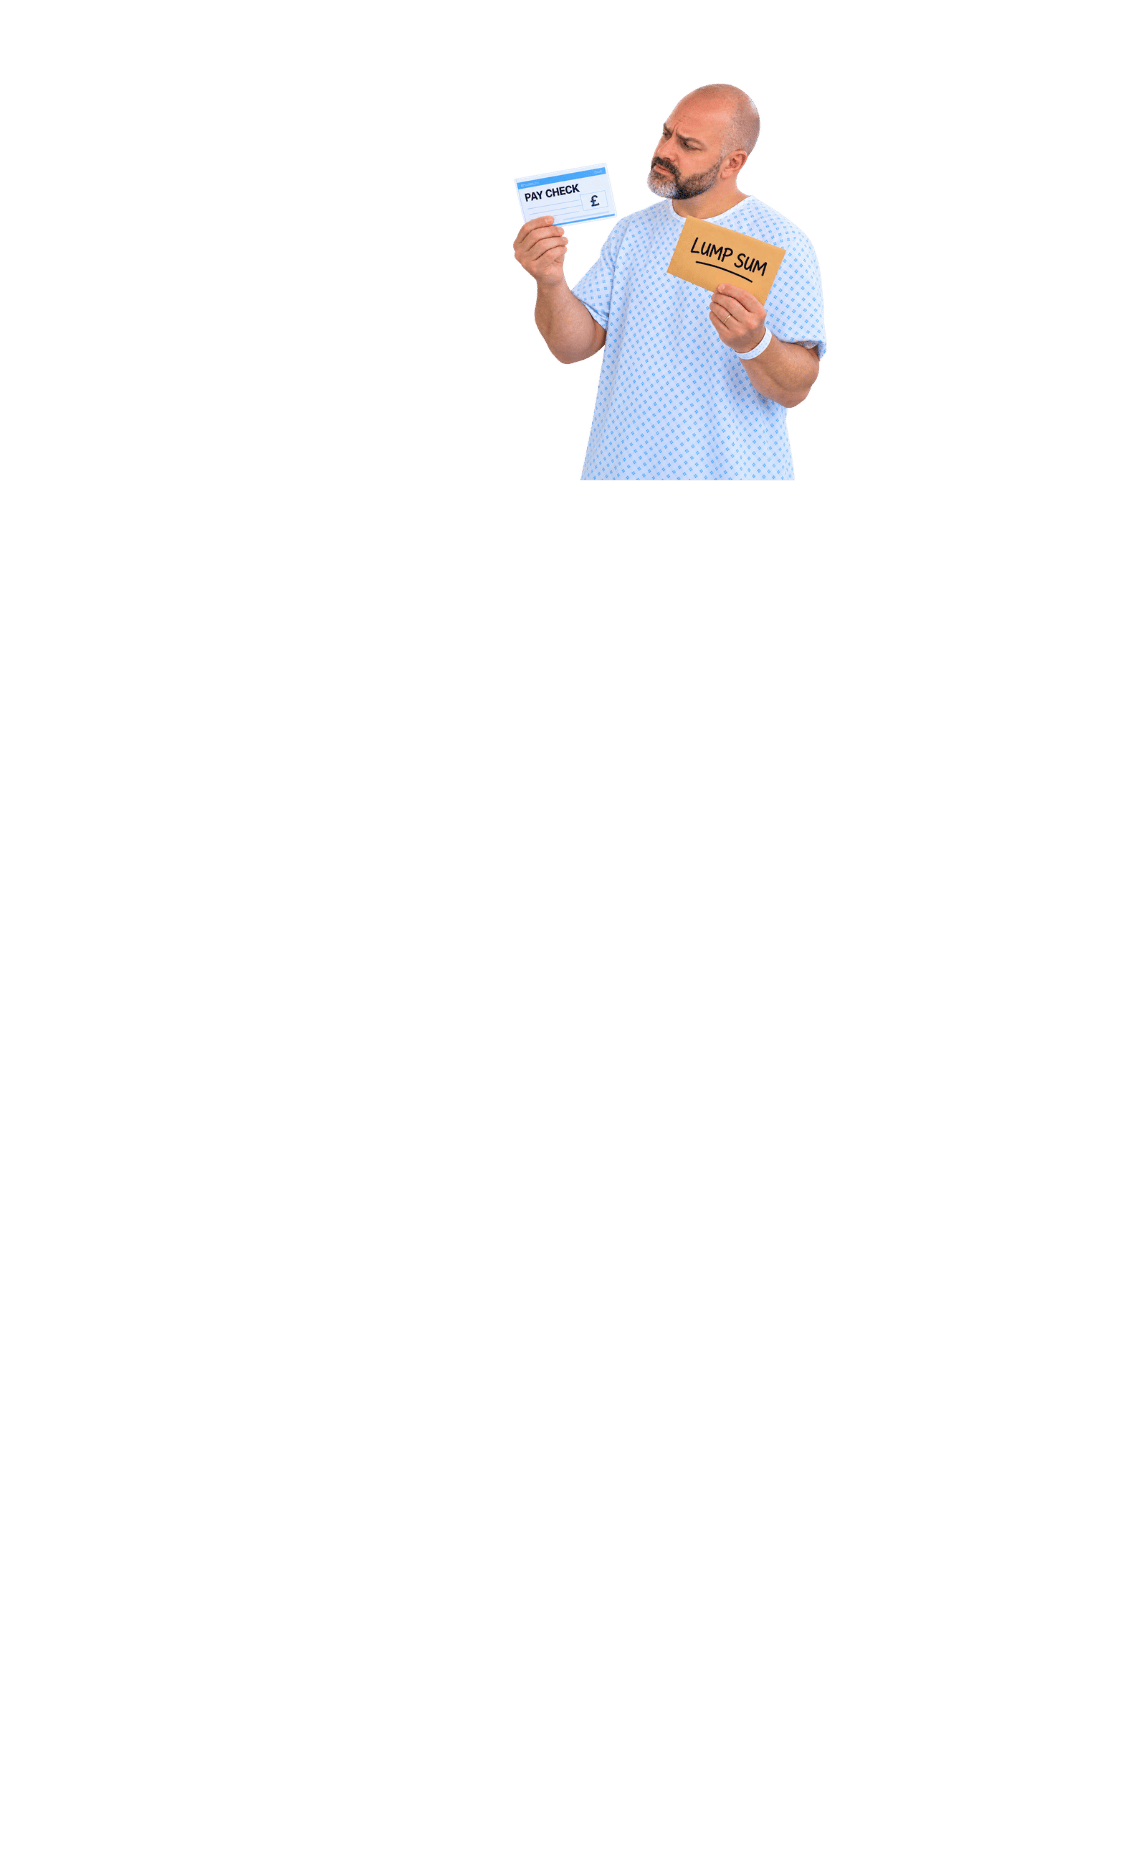
Critical Illness Cover
vs
Income Protection
What’s the difference?
First things first, they do different jobs — although sometimes both could help.
Critical Illness Cover usually pays a one-off lump sum if you’re diagnosed with a defined illness, and a full claim will normally bring that cover to an end.
Income Protection pays a monthly income if illness or injury stops you working. You can potentially claim more than once, and a claim could last a few months or continue for years.
So what is Critical Illness Cover for? Think big financial change — clearing the mortgage, reducing your hours or paying for private treatment after something serious.
Income Protection is about keeping money coming in when you can’t work, whether that’s because of illness, injury, a back problem or mental health.
You may be able to claim on both. The question isn’t which is better — it’s which problem you want the insurance to solve.
Start Quote
Your Critical Illness Cover questions answered
We love to answer your questions but if you don’t see what you’re looking for, get in touch!
Is Critical Illness Cover worth it?Let’s put it a different way. If you were diagnosed with something serious like cancer, would a tax-free lump sum of a year’s salary be useful? Could you take time off work, focus on recovery, spend more time with your family or clear some debt? If the answer is yes, then Critical Illness Cover may be worth it. The question is really what would a decent sum of money allow you to do at that moment?
Does Critical Illness Insurance cover all cancers?Not all cancers. Cancer has to meet the definition in your policy, and some earlier-stage or less severe cancers may not qualify for a full payment. Some policies also offer additional or smaller payments for certain early-stage cancers, so it’s worth understanding the differences between insurers.
Should Critical Illness Cover pay off my full mortgage?It can, but it doesn’t have to. Clearing the mortgage might be your priority, while someone else may prefer to protect a few years of income or spread the money across several needs. Your budget matters too. Start with what you’d want the money to solve if you were diagnosed tomorrow.
Do I need Critical Illness Cover if I already have sick pay or savings?You may still want both. Sick pay and savings can keep the everyday bills covered, while Critical Illness Cover can give you a larger lump sum for the bigger decisions like clearing debt, taking longer away from work or making changes at home. It comes down to your existing safety net, your budget and what you’d want money to give you the freedom to do.
Does Critical Illness Cover include children?Many policies include some level of children’s Critical Illness Cover, and some allow you to add enhanced children’s cover too. It’s worth understanding exactly what is included because the benefits can vary considerably. If your child became seriously ill, taking time away from work might suddenly matter more than almost anything else.
Can I get Critical Illness Cover with a pre-existing condition?Possibly. Having a medical history doesn’t automatically mean you can’t get cover, but an insurer may exclude a condition, charge more or offer different terms depending on your circumstances. Different insurers have different appetites for medical risk, so knowing where to apply first can make a real difference.
Do Critical Illness insurers actually pay claims?Yes. In 2025, insurers paid 90.2% of new Critical Illness claims, with around £1.42 billion paid across individual and group Critical Illness claims. Claims can still be declined, which is why understanding the policy definitions and answering the health questions fully and accurately when you apply really matters.
Start my review
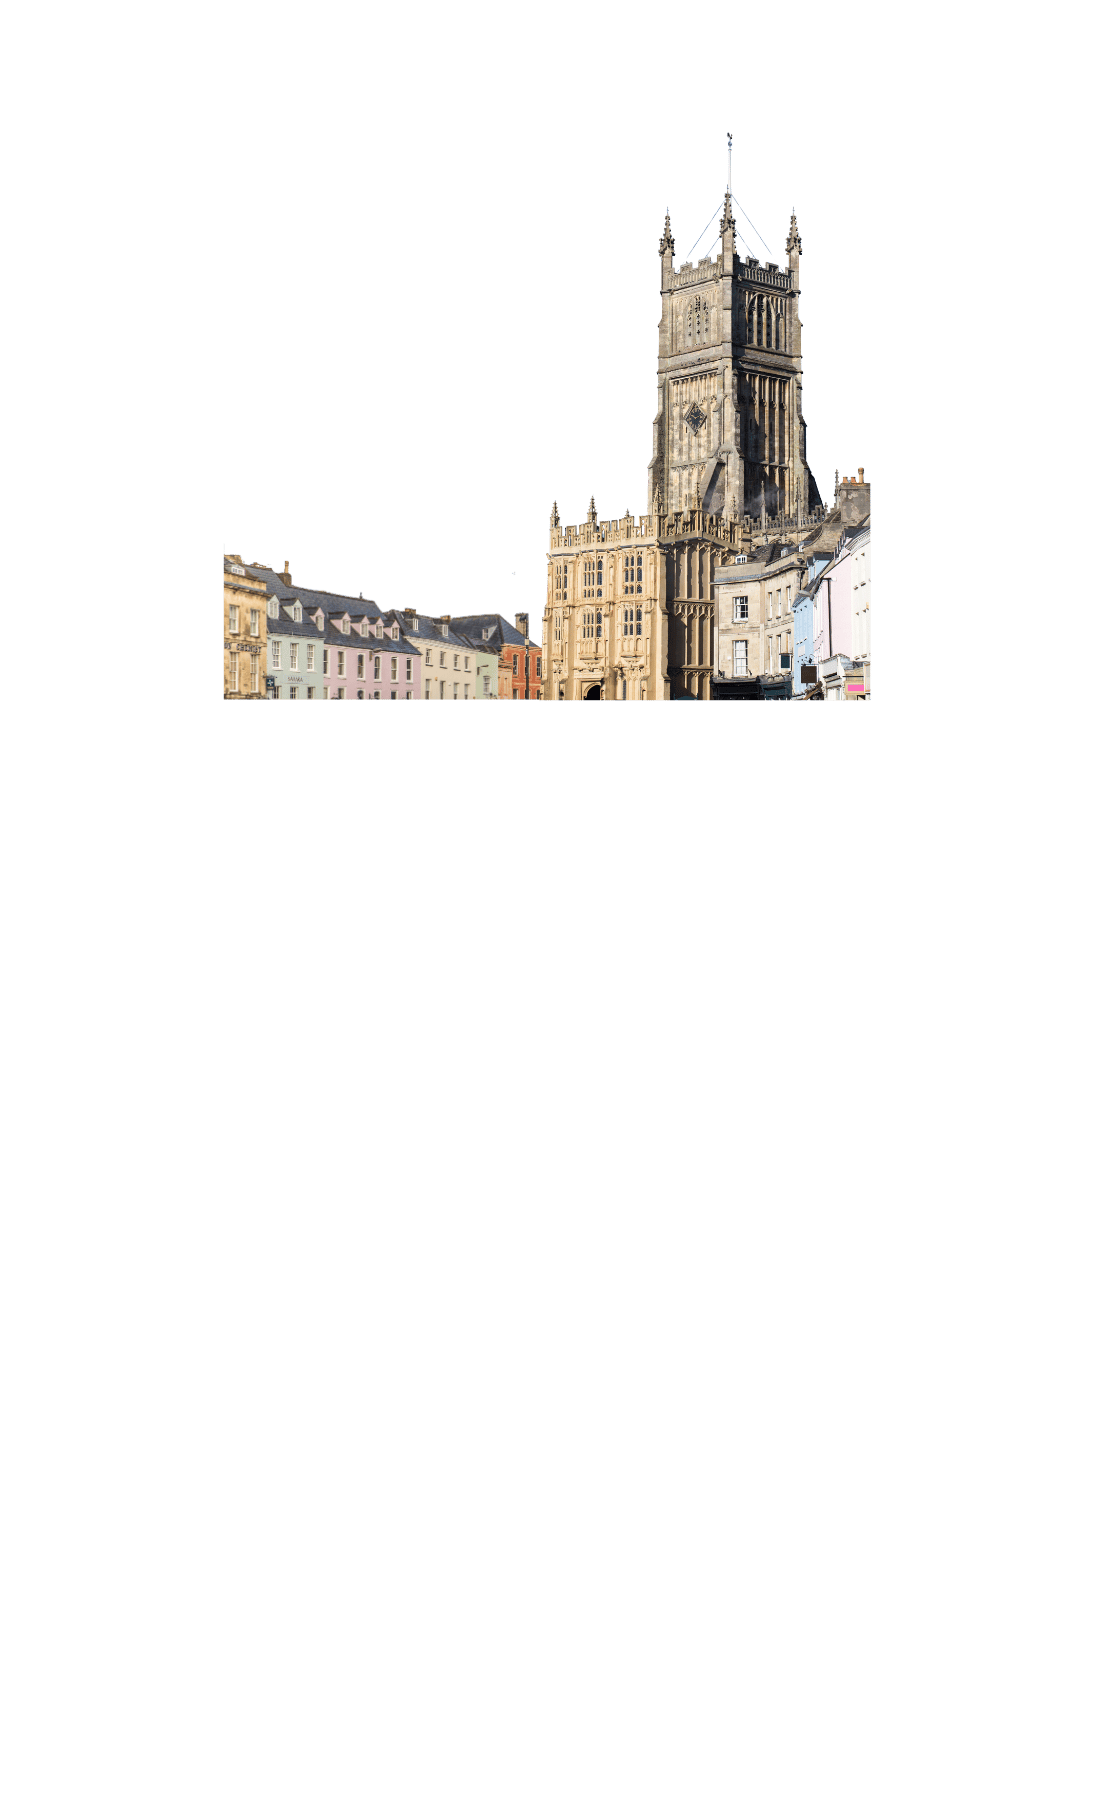
Local Service. Human Advice.
Critical Illness Cover advice in Cirencester and the Cotswolds.
A serious diagnosis affects more than your health. It can change work, income, family life and the plans you had for the future.
We help individuals and families across the Cotswolds and beyond understand what a cash lump sum could actually do for them if life suddenly changed. From protecting the mortgage to giving themselves more time and choices while they recover.
If you’re local, we can talk face-to-face. If you’re further away, the advice stays just as personal.
Start my review
What we do

About
Life can change before it ends
Real advice on Critical Illness Cover for individuals, families, business owners and employers
Get Critical Illness Cover Quotes
Critical Illness Cover helps protect the life you’re still living
1 in 2 people diagnosed with cancer are now expected to survive for 10 years or more
Surviving is the good news. But surviving can change your income, work, family life and finances.
Start my Critical Illness Cover review
What is Critical Illness Cover?
Critical Illness Cover, sometimes referred to as Serious Illness Cover pays a tax-free lump sum if you’re diagnosed with one of the serious illnesses covered by your policy. Cancer, heart attack and stroke are the best-known conditions, but many policies now cover dozens of others and can include children’s cover too.
Unlike life insurance that pays if you die, Critical Illness Cover pays if you survive a serious illness. The money is yours to use however you need it, often it’s used to pay off a mortgage, pay for private treatment, home improvements or simply to take time out of work to fully recover at your pace without the financial stress of needing to return to work.
Start my Critical Illness Cover review
How much Critical Illness Cover do I need & what does it cost?
Critical Illness Cover is priced around things like your age, health, smoking status, how long you want the cover for and the amount you choose. So for some people it may only cost a few pounds a month, for others it can be a lot more based on their circumstances and what they want the policy to cover.
So how much cover do you need? There isn’t one right answer. We start with what you’d want the money to do if you were diagnosed with something serious.
Would you want a year’s income so you could take time away from work? Clear the mortgage? Make changes at home? Or simply have enough money to give you and your family more choices while you recover?
Understanding why you want Critical Illness Cover is usually the best place to start working out how much you need. So, what would you want the money to do?
Get Critical Illness Cover Quotes
What does Critical Illness Insurance cover me for?
2 in 3 claims for cancer*
We’ve already talked about what you can do with the money. But what actually makes the policy pay?
Critical Illness Cover pays a lump sum when you’re diagnosed with one of the conditions covered by your policy and it meets the insurer’s definition.
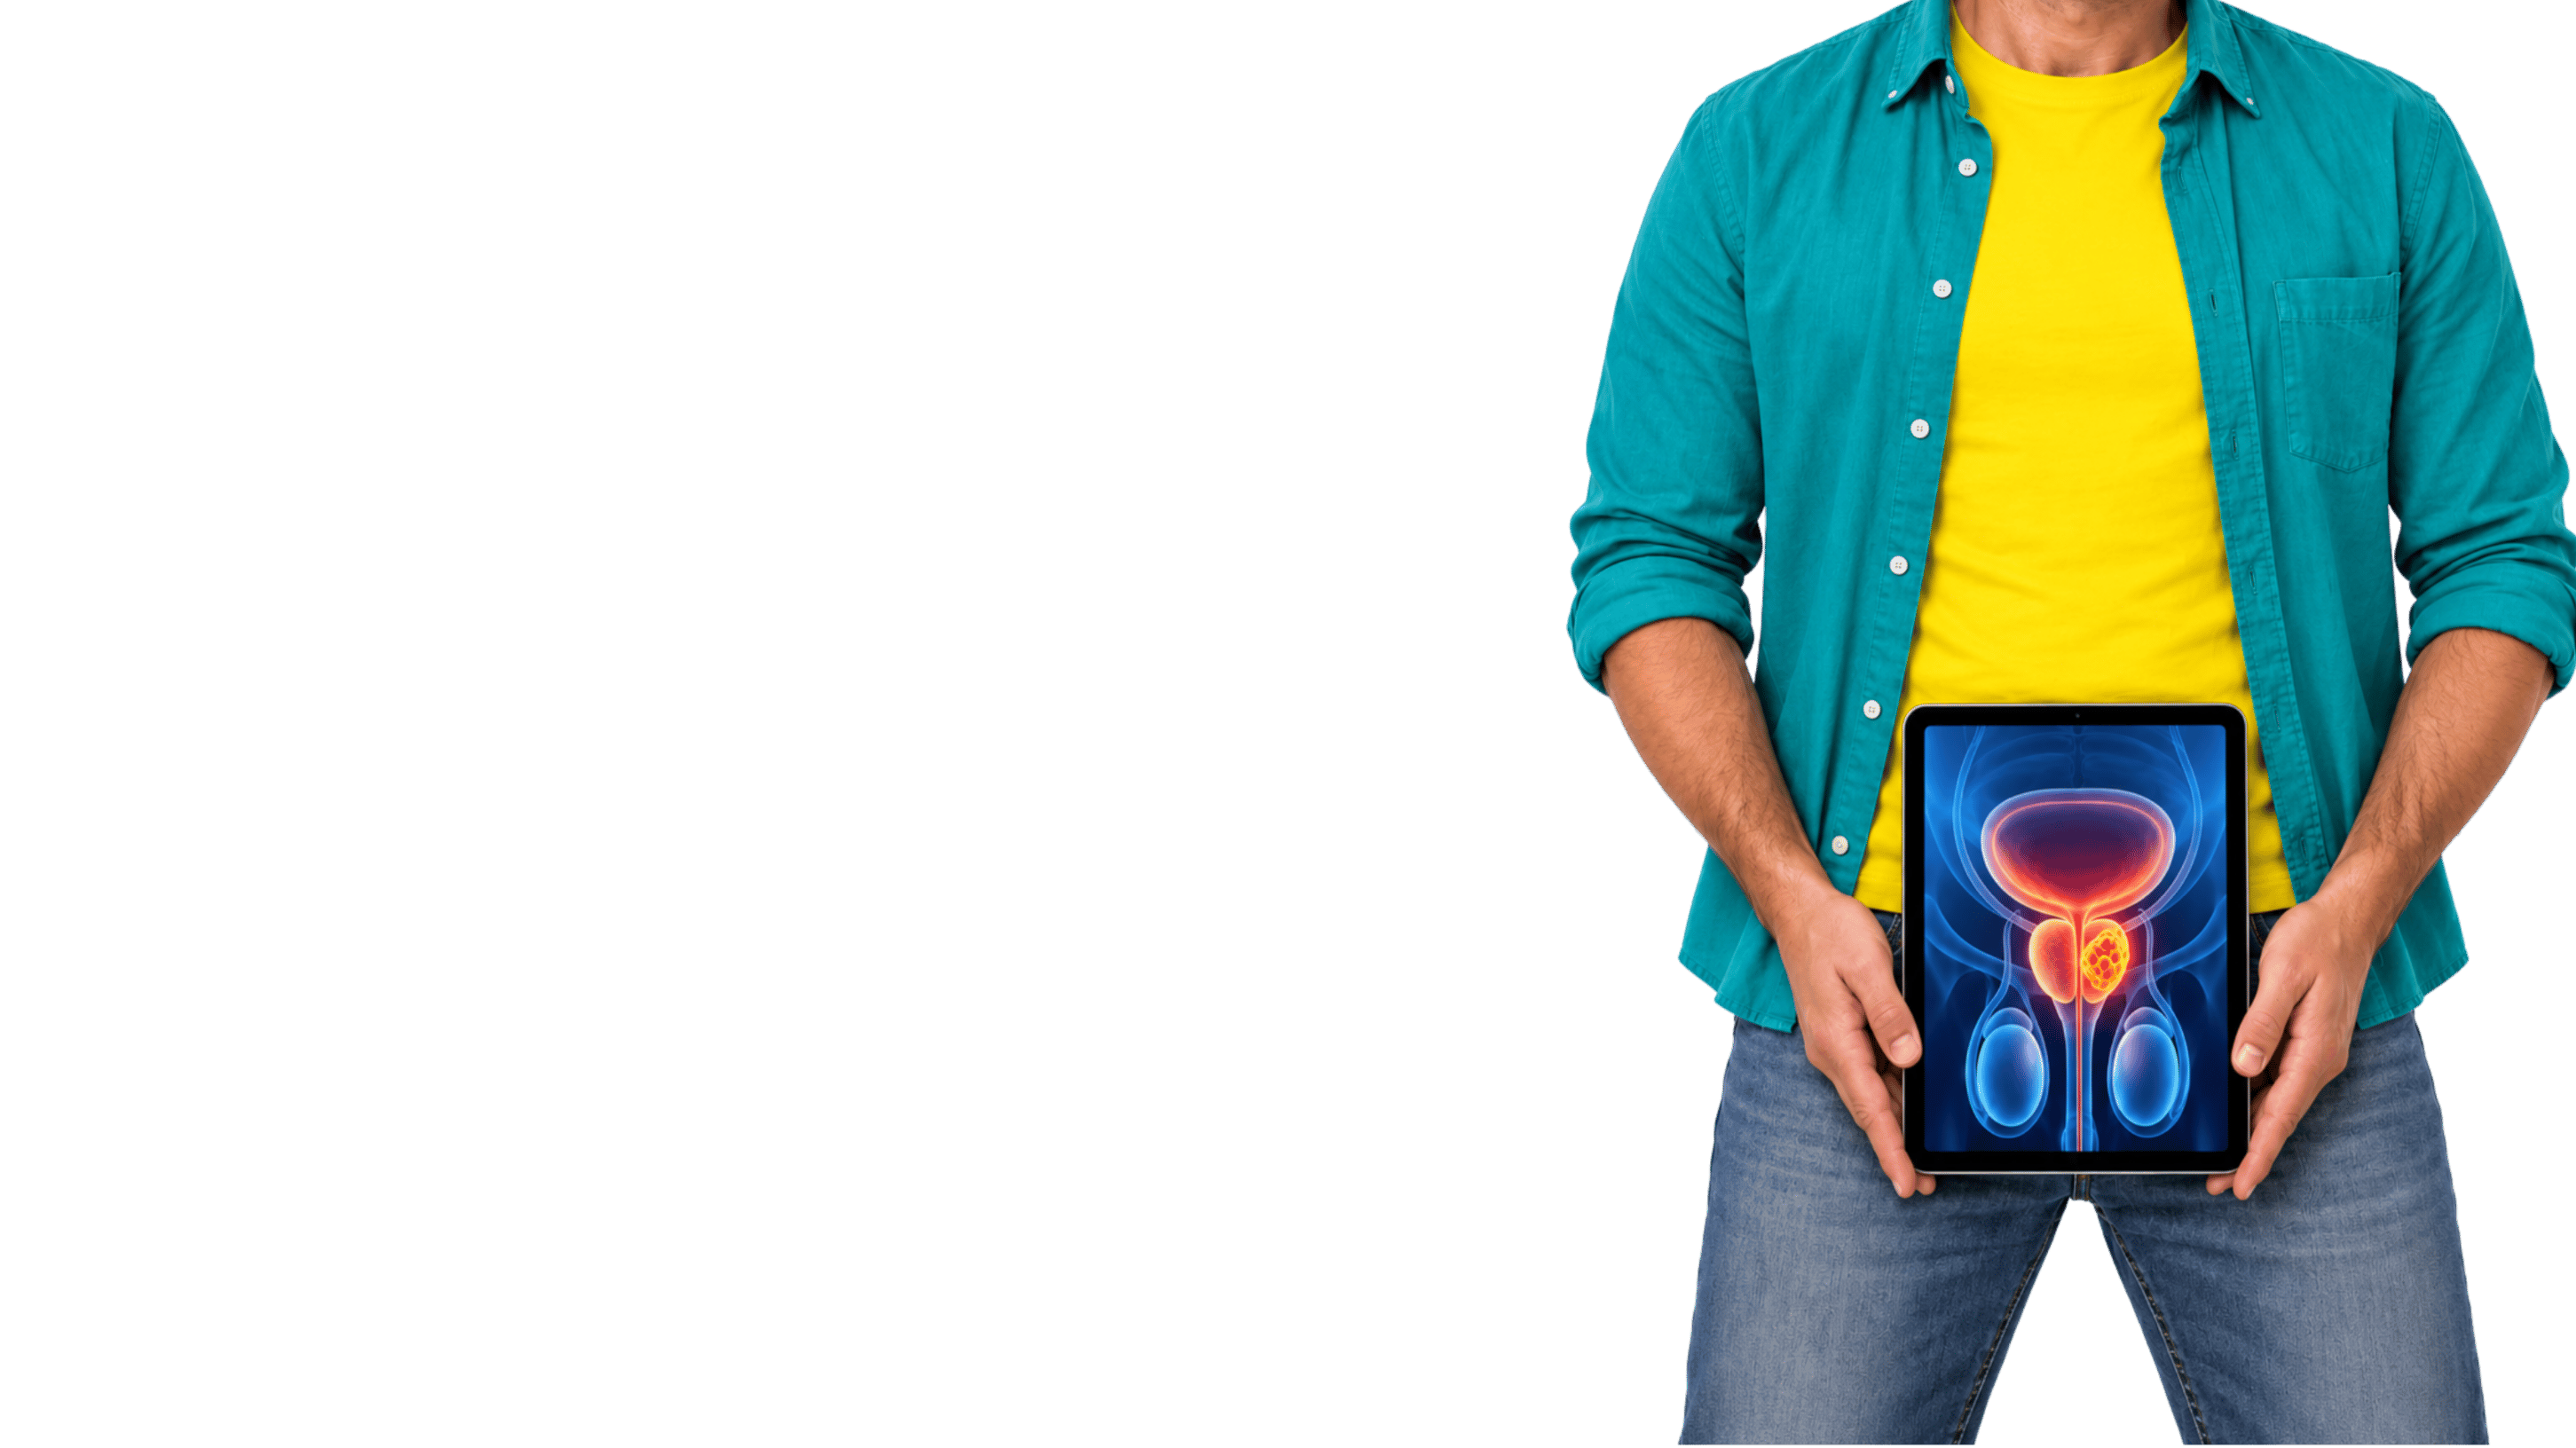
Cancer, Heart Attack and Stroke account for 8 in 10 claims*, but people also claim for things like multiple sclerosis, benign brain tumours, heart valve surgery, coronary artery bypass surgery and Parkinson’s disease.
Start my Critical Illness Cover review
We’ve got you...
We compare Critical Illness Cover and Serious Illness Cover from a range of leading insurers, including L&G, Aviva, Royal London, Guardian, Zurich and Vitality.
Comparing Critical Illness Cover isn’t just about price. We’ll help you understand the differences in cover that actually matter to you — whether you’re taking out your first policy or reviewing an existing one...
...we’re here to help.
Start my Critical Illness Cover review
£1.42 Billion paid in Critical Illness Claims*
UK insurers paid £1.42 billion in individual and group Critical Illness Cover claims in 2025*
*individual and group claims using data from the ABI and GRiD
For you
A serious diagnosis can change your health, work and plans overnight. A tax-free cash lump sum gives you more choices about what happens next.
For them
If you’re seriously ill, the people around you feel it too. If it’s your child who becomes ill, the impact can be even greater. Critical Illness Cover can help reduce some of the financial pressure on the whole family while you focus on what matters.
With us
“A passion for finding people the right insurance solutions. No pressure and on hand to answer questions. It was a pleasure dealing with him.” - David - Legacy Is Customer Review
Critical Illness Cover for your situation.
Individuals and Couples
Critical Illness Cover for you and/or your partner, helping protect your household finances and lifestyle if serious illness changes what you can do.
Business Owners & Directors
Personal Critical Illness Cover can protect your own finances, while business protection can help where illness affects the company too.
Children & Families
A serious illness can affect the whole family. Critical Illness Cover can help give better financial options if you or your child become seriously ill.
Critical Illness Cover vs Income Protection - What’s the difference?
First things first, they do different jobs — although sometimes both could help.
Critical Illness Cover usually pays a one-off lump sum if you’re diagnosed with a defined illness, and a full claim will normally bring that cover to an end.
Income Protection pays a monthly income if illness or injury stops you working. You can potentially claim more than once, and a claim could last a few months or continue for years.
So what is Critical Illness Cover for? Think big financial change — clearing the mortgage, reducing your hours or paying for private treatment after something serious.
Income Protection is about keeping money coming in when you can’t work, whether that’s because of illness, injury, a back problem or mental health.
You may be able to claim on both. The question isn’t which is better — it’s which problem you want the insurance to solve.
Start my Critical Illness Cover review
Your Critical Illness Cover questions answered
We love to answer your questions but if you don’t see what you’re looking for, get in touch!
Is Critical Illness Cover worth it?Let’s put it a different way. If you were diagnosed with something serious like cancer, would a tax-free lump sum of a year’s salary be useful? Could you take time off work, focus on recovery, spend more time with your family or clear some debt? If the answer is yes, then Critical Illness Cover may be worth it. The question is really what would a decent sum of money allow you to do at that moment?
Does Critical Illness Insurance cover all cancers?Not all cancers. Cancer has to meet the definition in your policy, and some earlier-stage or less severe cancers may not qualify for a full payment. Some policies also offer additional or smaller payments for certain early-stage cancers, so it’s worth understanding the differences between insurers.
Should Critical Illness Cover pay off my full mortgage?It can, but it doesn’t have to. Clearing the mortgage might be your priority, while someone else may prefer to protect a few years of income or spread the money across several needs. Your budget matters too. Start with what you’d want the money to solve if you were diagnosed tomorrow.
Do I need Critical Illness Cover if I already have sick pay or savings?You may still want both. Sick pay and savings can keep the everyday bills covered, while Critical Illness Cover can give you a larger lump sum for the bigger decisions like clearing debt, taking longer away from work or making changes at home. It comes down to your existing safety net, your budget and what you’d want money to give you the freedom to do.
Does Critical Illness Cover include children?Many policies include some level of children’s Critical Illness Cover, and some allow you to add enhanced children’s cover too. It’s worth understanding exactly what is included because the benefits can vary considerably. If your child became seriously ill, taking time away from work might suddenly matter more than almost anything else.
Can I get Critical Illness Cover with a pre-existing condition?Possibly. Having a medical history doesn’t automatically mean you can’t get cover, but an insurer may exclude a condition, charge more or offer different terms depending on your circumstances. Different insurers have different appetites for medical risk, so knowing where to apply first can make a real difference.
Do Critical Illness insurers actually pay claims?Yes. In 2025, insurers paid 90.2% of new Critical Illness claims, with around £1.42 billion paid across individual and group Critical Illness claims. Claims can still be declined, which is why understanding the policy definitions and answering the health questions fully and accurately when you apply really matters.
Start my Critical Illness Cover review
Local Service. Human Advice.
Critical Illness Cover advice in Cirencester and the Cotswolds.
A serious diagnosis affects more than your health. It can change work, income, family life and the plans you had for the future.
We help individuals and families across the Cotswolds and beyond understand what a cash lump sum could actually do for them if life suddenly changed. From protecting the mortgage to giving themselves more time and choices while they recover.
If you’re local, we can talk face-to-face. If you’re further away, the advice stays just as personal.
Start my review